Blog

FEATURED

Authentication Should Be Built Around Customer Segments

Banks spend considerable effort segmenting customers for products, communications, and risk. A mortgage customer is treated differently from a primary current account holder. A corporate treasurer has different needs from a retail savings customer. Yet when it comes to authentication, many banks still design around a single primary approach: mobile-first authentication.

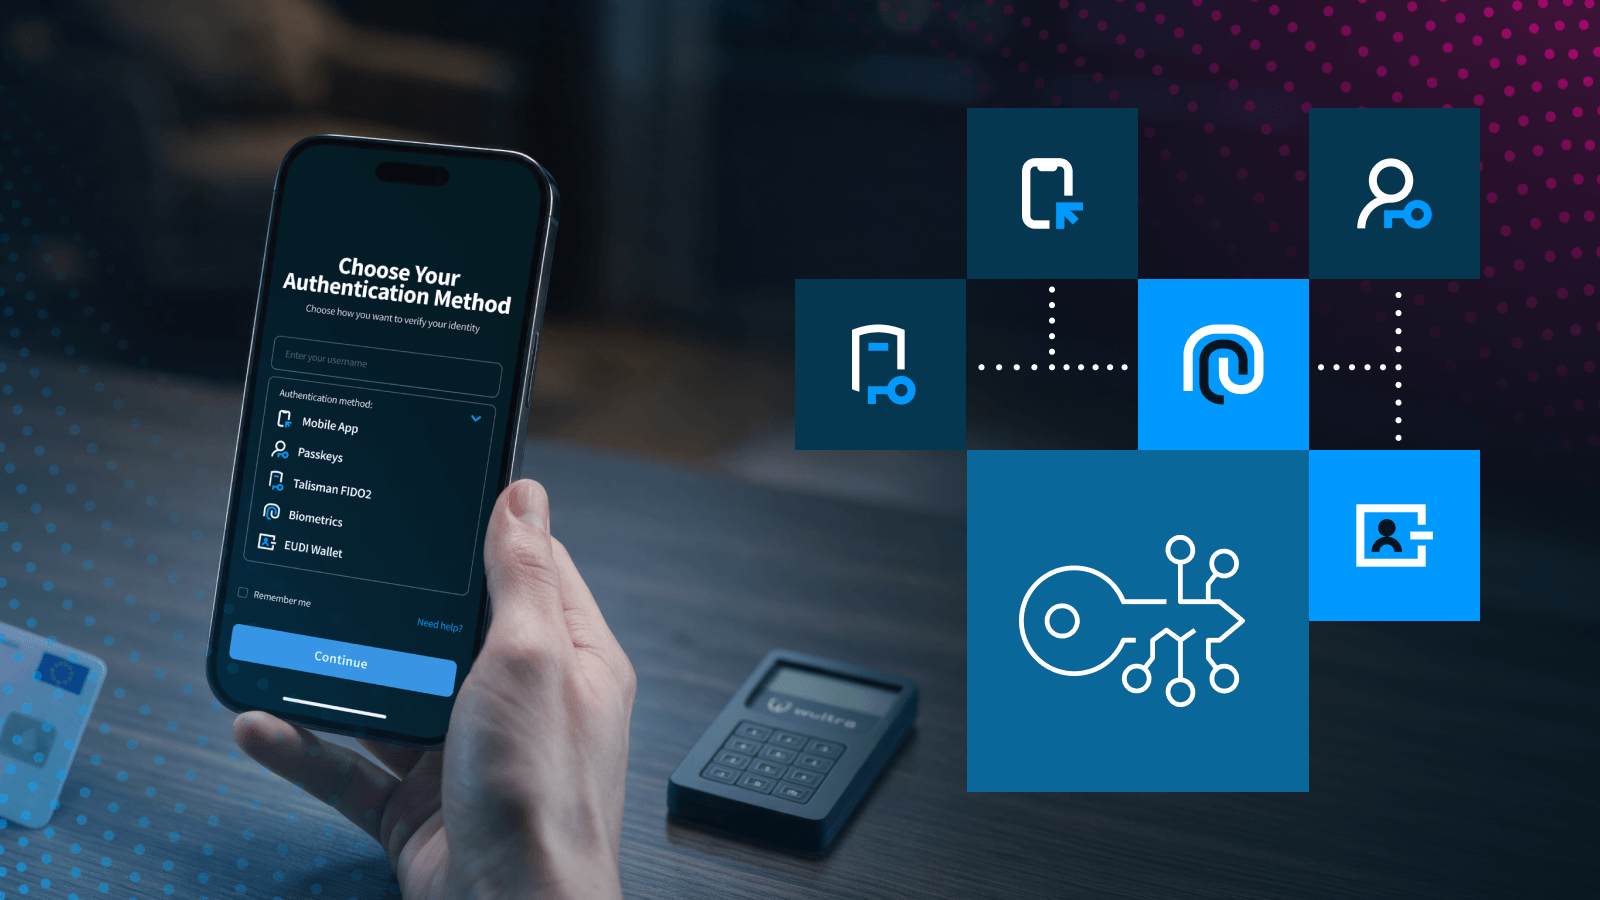
Authentication Flexibility Is Becoming a Strategic Capability for Banks

For most of the past decade, the authentication question banks asked was: Which method should we standardize on? Mobile apps provided a compelling answer, and most institutions converged on them. That question is now changing.

What Makes an Electronic Signing Process Trustworthy?

Choosing the right type of electronic signature is only part of building a reliable signing process. Banks also need to consider how the signer is identified and authenticated, how consent and document integrity are protected, and how evidence can be verified over time.

The Benefits of Single Sign-On for Digital Banking UX

This article looks at how authentication shapes the digital banking experience, why consistency matters across customer journeys, and how single sign-on helps create a more seamless user experience without compromising security.

Mobile App Security: Best Practices for Banking Apps

Building a secure mobile banking app involves more than adding security features at the end of development. Banks need to think about security throughout the entire application lifecycle, from design and authentication to application integrity, fraud monitoring, and ongoing maintenance.

Mobile In-App Protection vs. App Shielding: What’s the Difference?

Mobile applications increasingly operate in hostile environments. Unlike traditional server-side software, a mobile app runs on a device outside the organization’s control, where attackers may inspect its code, manipulate its runtime, modify the application package, or interfere with its operation.

Advanced vs. Qualified Electronic Signatures Explained

Not all electronic signatures provide the same level of assurance. Under the eIDAS Regulation, advanced electronic signatures (AES) and qualified electronic signatures (QES) each serve different purposes and have different legal characteristics. This article explains the differences, how each works, and why the distinction matters.

Wultra Recognized in Gartner® Hype Cycle™ for Digital Identity, 2026

Wultra has been recognized as the only Sample Vendor listed for post-quantum authentication in the Gartner® Hype Cycle™ for Digital Identity, 2026, for the second consecutive year.

Single Sign-On (SSO): How It Works for Banking Apps

Customers expect a consistent authentication experience across mobile banking, online banking, and connected financial services. Single Sign-On (SSO) helps banks deliver that experience by providing centralized access across multiple applications while maintaining strong control over authentication.

Identity Verification in Banking: What Banks Need to Know in 2026

Opening a bank account today rarely means walking into a branch. Customers expect to verify their identity remotely and on mobile, while banks are expected to catch fraud, meet regulatory requirements, and keep the process fast enough that applicants actually complete it. Identity verification is where those pressures meet.

Electronic Signatures in Banking: What Financial Institutions Need to Know

From loan agreements to onboarding documents, banks increasingly need ways to sign and verify sensitive transactions digitally without adding complexity to the customer experience. This article explores how electronic signatures are being used in banking today, what the different signature types mean in practice, and where institutions are focusing as digital signing becomes part of everyday banking operations.

Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.